

Over the last six months, Terex’s shares have sunk to $50.73, producing a disappointing 19.9% loss - a stark contrast to the S&P 500’s 12.8% gain. This may have investors wondering how to approach the situation.
Given the weaker price action, is now the time to buy TEX? Find out in our full research report, it’s free.
Why Does TEX Stock Spark Debate?
With humble beginnings as a dump truck company, Terex (NYSE:TEX) today manufactures lifting and material handling equipment designed to move and hoist heavy goods and materials.
Two Positive Attributes:
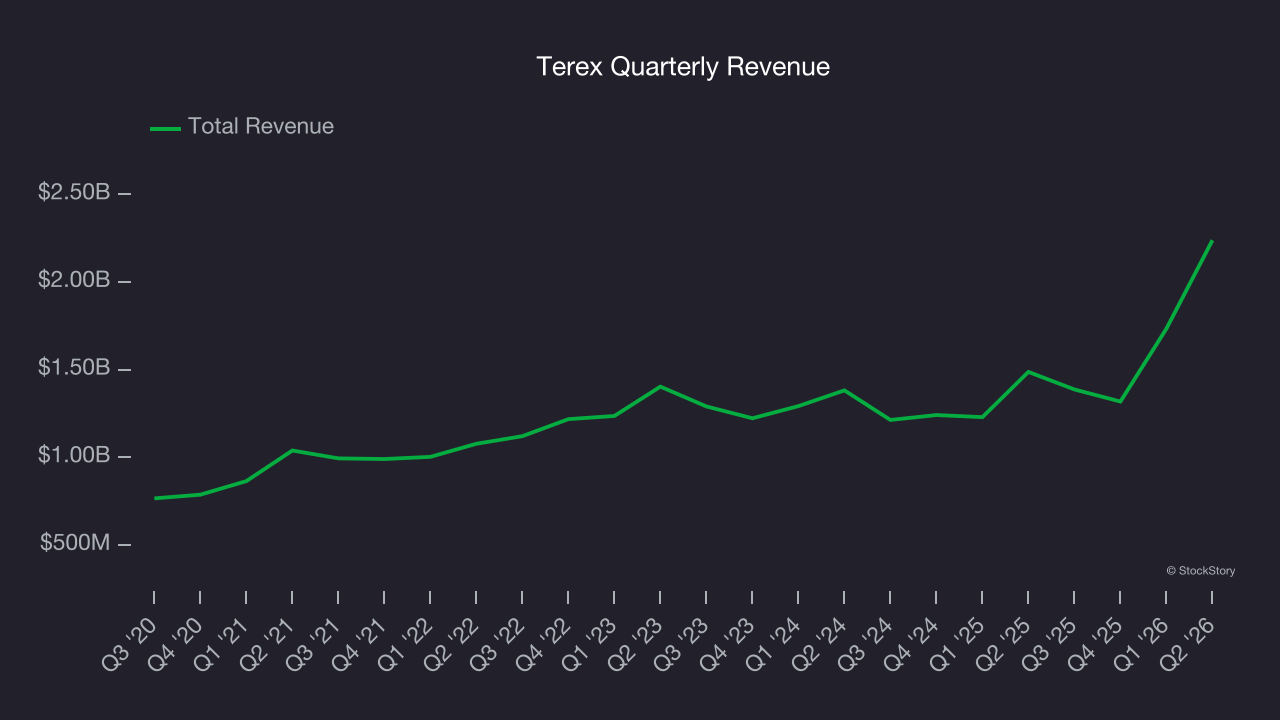
1. Skyrocketing Revenue Shows Strong Momentum
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Over the last five years, Terex grew its sales at an exceptional 14.1% compounded annual growth rate. Its growth beat the average industrials company and shows its offerings resonate with customers.
2. Increasing Free Cash Flow Margin Juices Financials
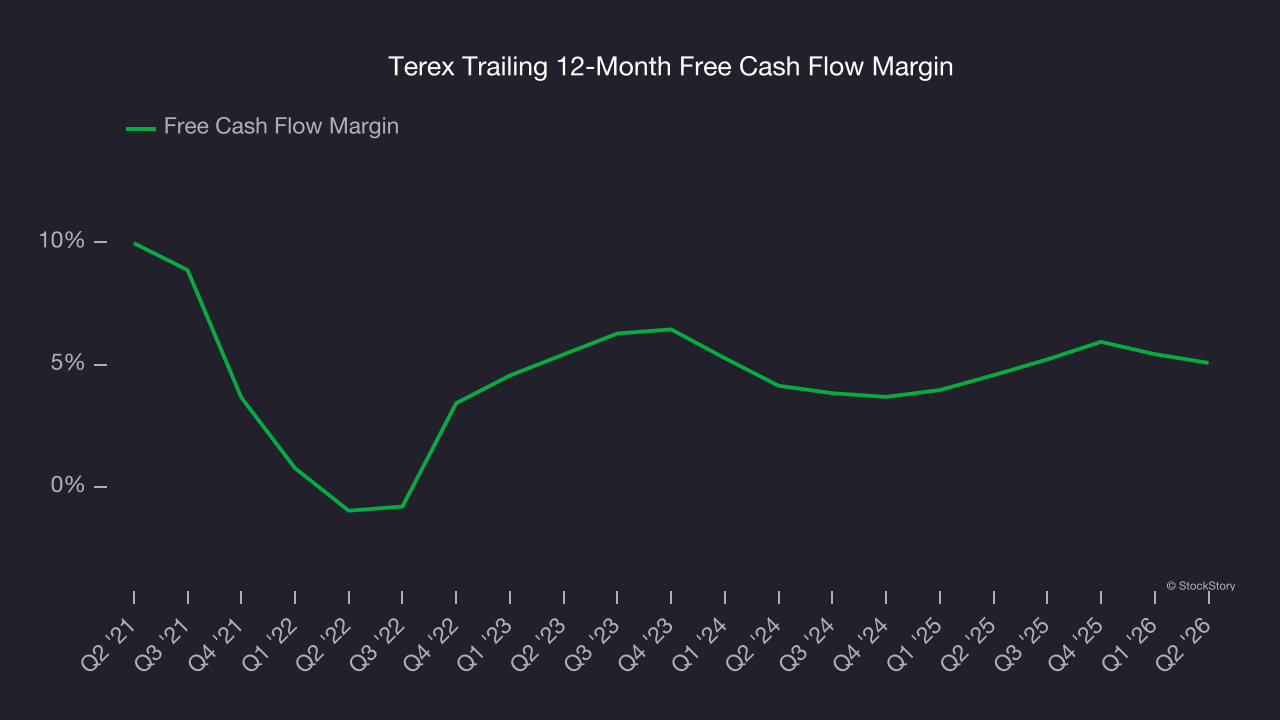
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
As you can see below, Terex’s margin expanded by 6 percentage points over the last five years. The company’s improvement shows it’s heading in the right direction, and we can see it became a less capital-intensive business because its free cash flow profitability rose while its operating profitability fell. Terex’s free cash flow margin for the trailing 12 months was 5.1%.
One Reason to Be Careful:
New Investments Fail to Bear Fruit as ROIC Declines
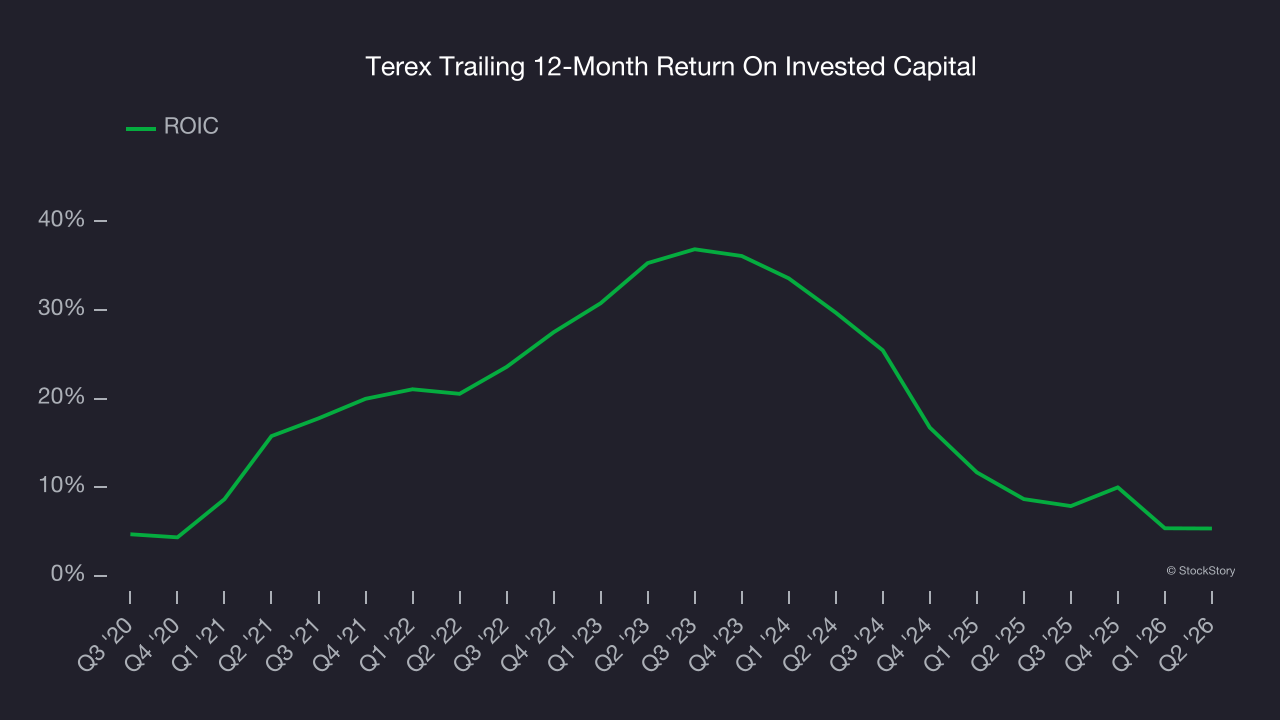
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
Over the last few years, Terex’s ROIC has unfortunately decreased significantly. Only time will tell if its new bets can bear fruit and potentially reverse the trend.
Final Judgment
Terex’s positive characteristics outweigh the negatives. With the recent decline, the stock trades at 9.7× forward P/E (or $50.73 per share). Is now a good time to buy? See for yourself in our full research report, it’s free.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.