
Marsh currently trades at $172.72 per share and has shown little upside over the past six months, posting a small loss of 1.8%. The stock also fell short of the S&P 500’s 15.2% gain during that period.
Is now the time to buy MRSH? Find out in our full research report, it’s free.
Why Does Marsh Spark Debate?
With roots dating back to 1871 and a presence in over 130 countries, Marsh (NYSE:MRSH) is a global professional services firm that helps organizations manage risk, strategy, and workforce challenges through its four specialized businesses.
Two Things to Like:
1. Long-Term Revenue Growth Shows Strong Momentum
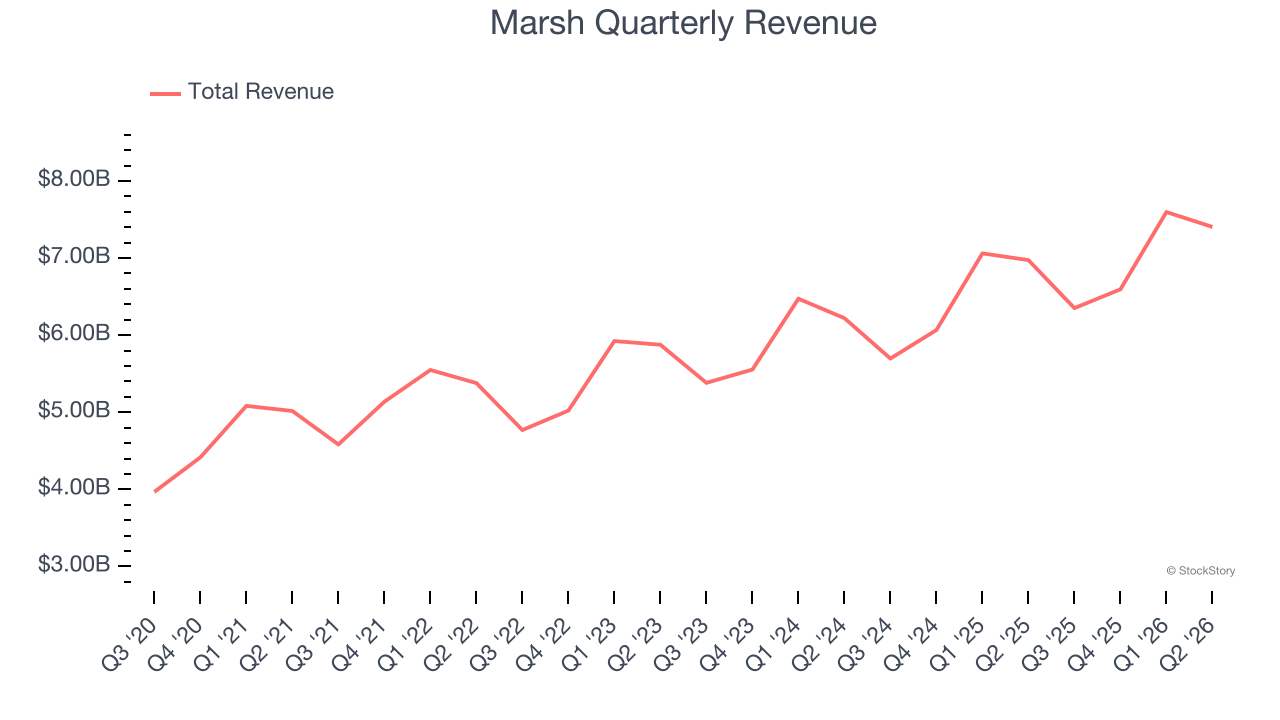
A company’s long-term sales performance can indicate its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Luckily, Marsh’s sales grew at a solid 8.6% compounded annual growth rate over the last five years. Its growth surpassed the average business services company and shows its offerings resonate with customers.
2. Excellent Free Cash Flow Margin Boosts Reinvestment Potential
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
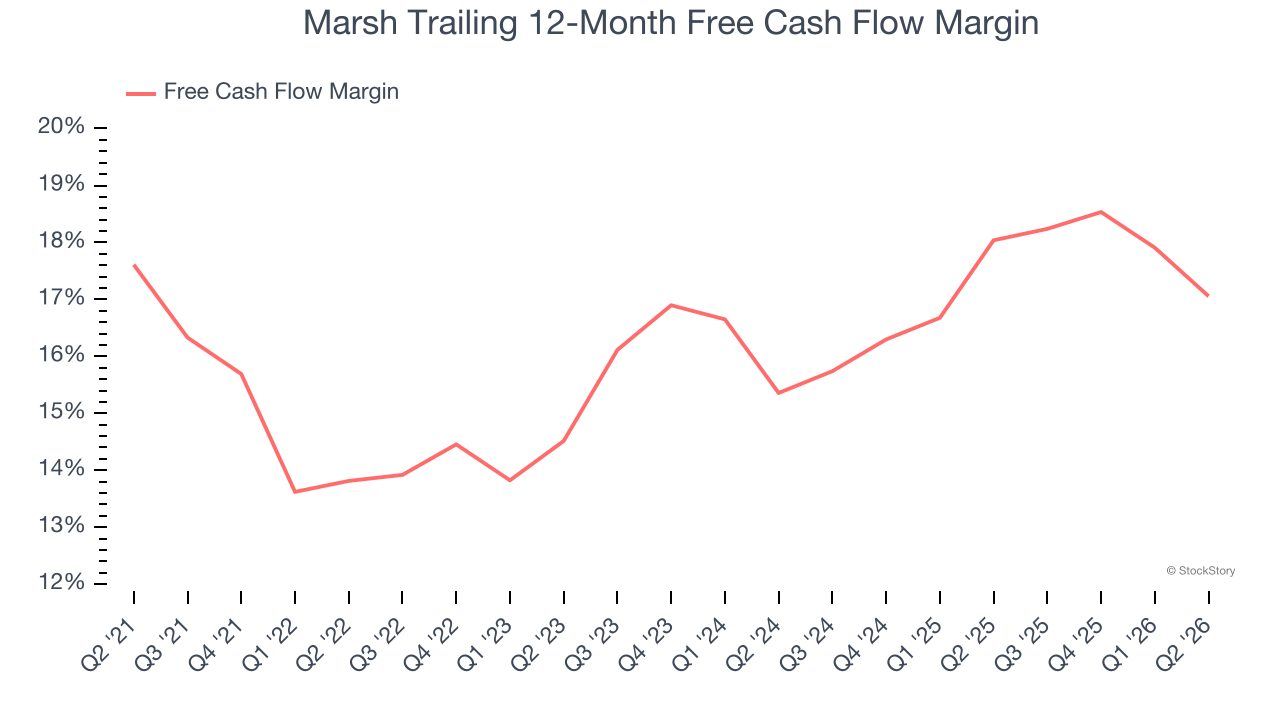
Marsh has shown terrific cash profitability, enabling it to reinvest, return capital to investors, and stay ahead of the competition while maintaining an ample cushion. The company’s free cash flow margin was among the best in the business services sector, averaging 15.9% over the last five years.
One Reason to Be Careful:
Slow Organic Growth Suggests Waning Demand In Core Business
In addition to reported revenue, organic revenue is a useful data point for analyzing Insurance Brokers companies. This metric gives visibility into Marsh’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, Marsh’s organic revenue averaged 4.6% year-on-year growth. This performance slightly lagged the sector and suggests it may need to improve its products, pricing, or go-to-market strategy, which can add an extra layer of complexity to its operations. 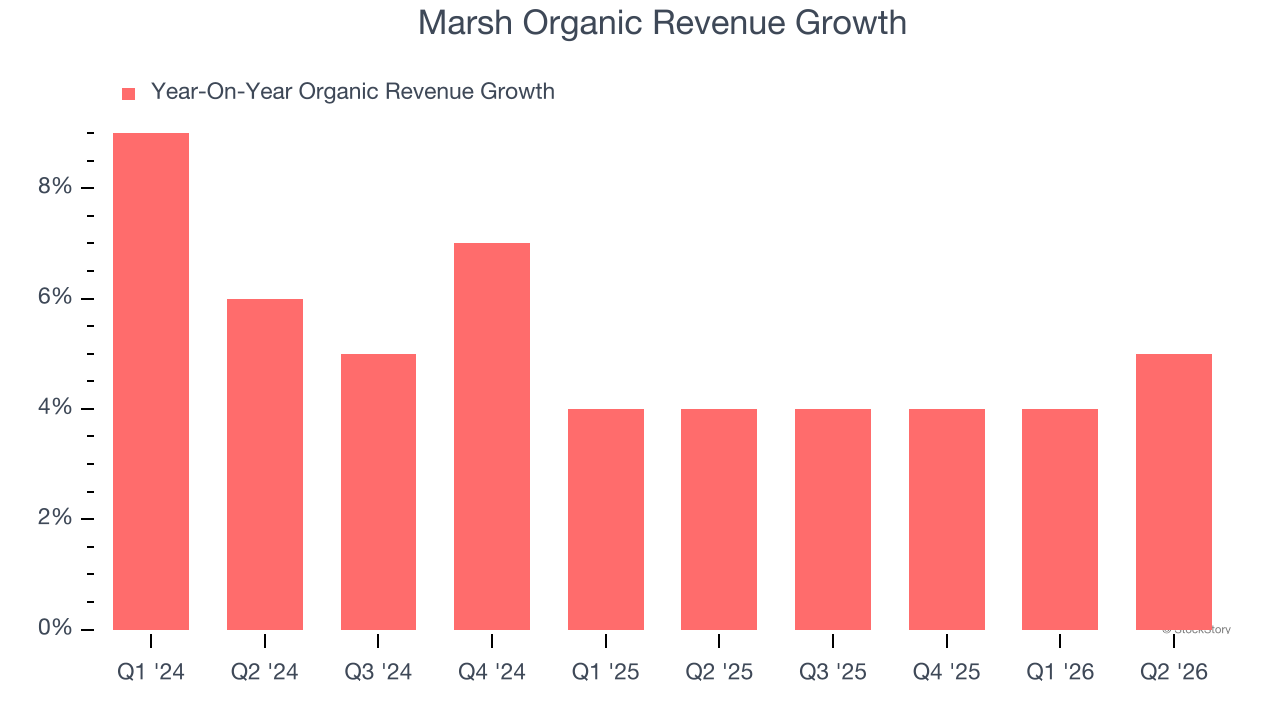
Final Judgment
Marsh’s merits more than compensate for its flaws. With its shares lagging the market recently, the stock trades at 15.6× forward P/E (or $172.72 per share). Is now the time to initiate a position? See for yourself in our full research report, it’s free.
Stocks We Like Even More Than Marsh
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.